
If you rent out a property, you need landlord insurance, not a standard homeowner policy. Homeowner cover is built for owner-occupiers, so it usually excludes the specific risks that come with tenants: loss of rental income, malicious damage, and legal costs to evict a non-paying tenant. Everything below explains what changes, when a homeowner policy might still hold up, and how to choose cover that actually pays out when a tenancy goes wrong.
TL;DR:
- Landlord insurance covers loss of rent, legal costs, and malicious tenant damage, which homeowner policies typically exclude or limit.
- Insurers often require a minimum occupation period before loss-of-rent claims become payable, especially for long-term rentals.
- Rental income protection is essential for tenant non-payment, early lease termination, or tenants absconding, and is usually sold as a separate product.
- Premium costs are higher due to increased risk factors like location, property type, rent level, and claims history, but can be reduced with proper tenant screening and security measures.
- When choosing insurance, clearly define occupancy status, contents needs, vacancy conditions, and confirm coverage details like waiting periods and claim limits before purchasing.
Table of Contents
- Homeowner vs landlord insurance: how the cover actually differs
- When does a homeowner policy still work for a rented property?
- What landlord-specific add-ons actually protect
- What drives landlord insurance premiums up or down
- Choosing cover: a checklist before you sign anything
- Why rental income protection matters more than most landlords realise
- Insurance as income protection, not just property protection
- Get cover built for what landlords actually risk
- Sources
Homeowner vs landlord insurance: how the cover actually differs
The building itself is often insured similarly under both policy types. Bricks, roof, fixed structures, geysers, and permanent fittings tend to fall under structural cover whether you live in the property or rent it out. Where the two diverge sharply is everything connected to occupancy, income, and liability.
Contents cover is the first fault line. A homeowner policy insures your own possessions. Once you’re renting the property out, your furniture (if it’s a furnished let) needs to be insured under a landlord policy, and your tenant’s belongings are never your responsibility to insure. That split matters because tenants often assume the landlord’s policy protects their possessions. It does not. Insurance responsibility follows insurable interest: you insure the structure and any furniture you own, tenants insure their own belongings and ideally carry their own liability cover.
Liability is the second. Homeowner liability cover typically protects you against claims from visitors. Landlord liability extends that to tenants and their guests, covering incidents like a broken stair injuring someone during their tenancy. This is worth checking closely, since limits vary and gaps here can be expensive if a tenant is hurt on the property.
The third, and often the one landlords overlook until it’s too late, is loss of rent versus loss of use. A homeowner policy typically pays your additional living expenses if you’re forced out of your own home after a fire or flood. Landlord policies instead pay you the rent you’d have earned if the property becomes uninhabitable, or in some cases if a tenant defaults, addressing the rental income gap that homeowner cover was never built for.
Watch for these common differences when comparing quotes:
- Waiting periods: landlord policies often require the tenant to have occupied the property for a minimum period before a loss-of-rent claim is payable.
- Furnished vs unfurnished: contents cover only applies if you’ve declared the property as furnished and listed what you own inside it.
- Vacancy clauses: most homeowner and landlord policies both limit or exclude cover once a property sits empty beyond a set number of days.
- Malicious damage: intentional tenant damage is frequently a separate add-on, not automatic under basic landlord cover.
- Undeclared letting: letting a property without telling your insurer is one of the fastest ways to void a homeowner policy entirely.
When does a homeowner policy still work for a rented property?
Not every letting arrangement automatically requires a full landlord policy, but the exceptions are narrower than most owners assume.
- Occasional letting. If you rent out a room or your whole home for a handful of weeks a year, some homeowner insurers will extend cover if you disclose the arrangement in advance. This is the exception, not the rule, and it rarely covers loss of rent.
- Short-term or holiday lets. These carry higher turnover and higher risk of damage, so insurers usually demand a dedicated short-term rental policy or an endorsement, rather than relying on a standard homeowner or even a standard landlord product.
- Long-term, continuous rental. Once you’ve handed over a lease for six or twelve months, you’ve moved from occasional use to a rental business in the insurer’s eyes. Landlord cover becomes the expectation, and a homeowner policy left unchanged can be void from the point letting began, since insurers can exclude claims linked to undisclosed rental use.
- Vacant properties. A property standing empty between tenants, or while you renovate, usually needs separate unoccupied-property cover. Insurers treat vacancy as higher risk for vandalism, burst pipes, and undetected damage.
When you speak to your insurer, say plainly how the property is used: continuous letting, occasional letting, holiday rental, or currently vacant. Guessing at the right category is how claims get rejected.
What landlord-specific add-ons actually protect
This is where landlord insurance earns its premium. The core add-ons exist because rental income, not just the building, is the asset at risk.
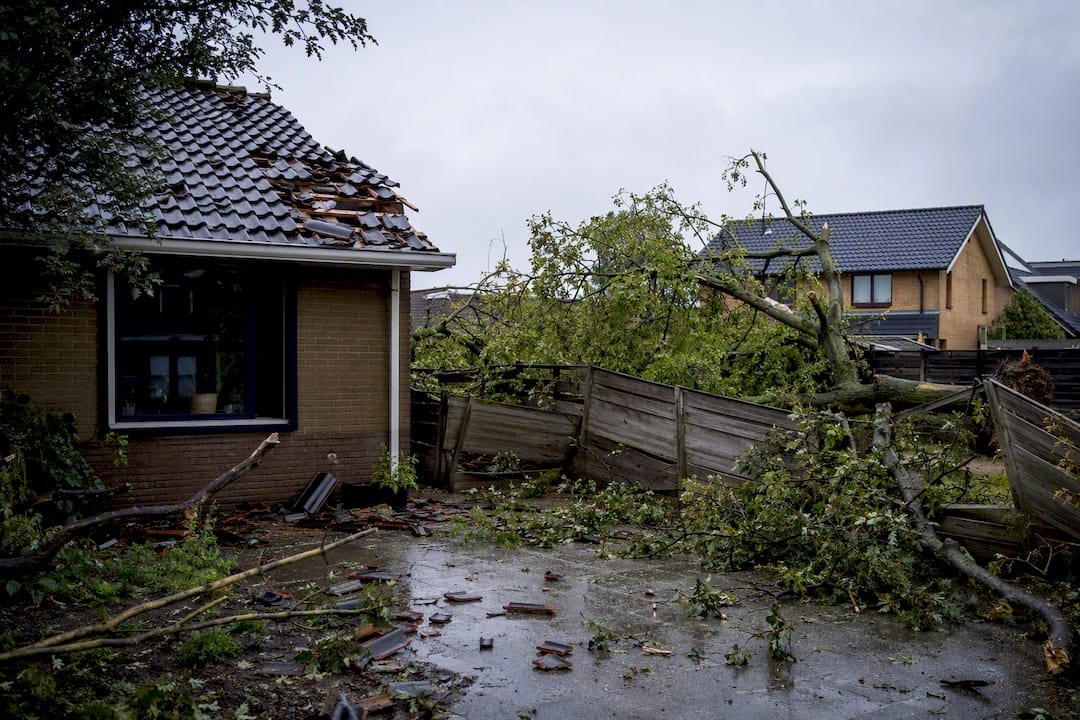
Loss of rent cover pays out when the property becomes uninhabitable through an insured event, such as fire or storm damage, or in some policies when a tenant simply stops paying. Cover typically runs for a set number of months and some insurers apply a minimum tenancy period before a claim becomes payable, so check that detail before you assume you’re covered from day one of a lease.
Legal and eviction cost cover usually pays for the legal process of removing a non-paying or non-compliant tenant, which in South Africa can run for months through the courts. This is separate from loss-of-rent cover; one replaces the income, the other pays the legal bill to get your property back.
It’s worth being precise about terminology here. Landlord liability cover protects you if a tenant or visitor is injured on the property and sues. Rental income insurance is a different product entirely, built specifically around tenant non-payment, early lease termination, and absconding, rather than physical injury claims. Landlords sometimes assume one covers the other. It doesn’t.
Malicious or intentional tenant damage (holes punched in walls, stripped fittings, deliberate vandalism on move-out) is frequently excluded from basic landlord policies and sold as a separate rider. Given how common this is at the end of a difficult tenancy, it’s one of the first things to confirm.
- Loss of rent: check the maximum payout period and any tenancy-length condition.
- Legal/eviction costs: confirm whether it covers court fees, attorney fees, or both.
- Malicious damage: ask whether it’s included or must be purchased separately.
- Rental income protection: check whether tenant non-payment and absconding are explicitly named perils.
Pro Tip: Ask your insurer for a worked example of a three-month rent-loss claim before you sign. Seeing the actual numbers, including any excess and waiting period, tells you far more than comparing headline premiums.
What drives landlord insurance premiums up or down
Is landlord insurance more expensive than a homeowner policy? Usually, yes, and it’s not arbitrary. Landlord premiums reflect genuine additional risk: a rented property changes occupants, gets less day-to-day maintenance attention from the owner, and carries income exposure a homeowner policy never has to price in.
The main drivers are:
- Location and crime statistics for the suburb, which affect burglary and malicious damage risk.
- Rent level, since higher rent means a bigger loss-of-rent liability for the insurer to cover.
- Construction type and property age, affecting both repair cost and claim likelihood.
- Claims history, both yours and, where insurers can assess it, the property’s.
- Excess and sum insured choices, where a higher excess generally lowers your monthly premium.
You can influence several of these directly. Screening tenants properly before signing a lease reduces default risk, which some insurers reward with lower rental income premiums. Basic security measures, working locks, alarm systems, and routine geyser maintenance, can avoid exclusions altogether and sometimes unlock discounts. Regular inspections between tenancies catch small maintenance issues before they become expensive claims. If you’re building a portfolio, ask about a multi-property landlord policy, which is often simpler to administer and more cost-effective than insuring each unit separately.
Choosing cover: a checklist before you sign anything
Work through this before comparing quotes, not after.
- Confirm occupancy status. Is the property continuously let, occasionally let, a short-term rental, or currently vacant? Each answer points to a different policy type.
- Decide furnished or unfurnished. This determines whether you need contents cover at all, and how much.
- Check your bond conditions. Most mortgage lenders require the property owner to maintain adequate building insurance throughout the loan term, and some specify it must reflect rental use once tenanted.
- Ask about waiting periods. How long must a tenant occupy the property before loss-of-rent cover activates?
- Ask what voids the policy. Undeclared letting, extended vacancy, and unreported renovations are the usual culprits.
- Confirm malicious damage is included or costed separately.
- Check the loss-of-rent cap. Is it a fixed number of months, or a percentage of the sum insured?
- Ask for the legal-cost cover scope. Does it include attorney fees, court fees, or both?
Red flags worth a follow-up call: vague wording around “reasonable wear and tear,” a loss-of-rent limit that seems disconnected from your actual monthly rent, or an insurer who can’t clearly explain their tenant-default definition. If you can’t get a straight answer on any of these, get a second quote.
Pro Tip: Keep a signed copy of every lease and your latest rent roll on file. When you claim, insurers will ask for proof of the rent you were actually receiving, not the market estimate.
For a deeper look at liability specifically, see this guide on public liability cover for landlords, and for a broader view of policy types available to South African property owners, this overview of landlord insurance products is a useful starting point.
Why rental income protection matters more than most landlords realise
Rental income insurance exists for the exact scenario homeowner cover ignores: a tenant who stops paying, breaks the lease early, or disappears altogether. Rent arrears aren’t a fringe concern either, with PayProp’s Rental Index recording a significant portion of tenants in arrears in one recent quarter, a figure that puts real pressure on landlords relying on that income to cover bond repayments.
A common scenario involves a tenant stopping rent payments part-way through a lease who refuses to leave. Rental income insurance can cover the lost rent while eviction proceedings run their course, and separately fund the legal costs of that eviction. Homeowner insurance offers nothing in this situation, because there’s no physical damage to claim against.
- Tenant non-payment: income replaced while arrears build and legal action proceeds.
- Early lease termination: cover for the income gap while you find a new tenant.
- Absconding tenants: protection when a tenant vacates without notice, leaving rent unpaid.
If any of these scenarios sound familiar, the rental income protection guide walks through claim examples in more detail.
Insurance as income protection, not just property protection
Most landlords still think of insurance as protecting bricks and mortar. The more useful mindset treats it as protecting a monthly income stream that your bond, your maintenance budget, and often your retirement planning depend on. Review your policy every year, not just when you buy a new property, and vet tenants properly before handing over keys. Run through a checklist before you decide, rather than defaulting to whatever your homeowner insurer offers.
— Coert
Get cover built for what landlords actually risk
Rentalincomeinsurance exists for the exact gap this article has been describing: the space between what a homeowner policy pays and what a landlord actually needs when rent stops coming in. Where a standard building policy leaves you exposed to a defaulting tenant, a lease broken early, or a tenant who simply vanishes, rental income insurance is built specifically to cover tenant non-payment, early lease termination, absconding, and the legal fees that come with evicting a tenant who won’t leave.

If you’re renting out a residential or commercial property and your current cover doesn’t name these risks explicitly, that’s worth fixing before your next lease starts, not after a tenant stops paying. It suits landlords with a single rental unit just as much as property managers and body corporates managing several. Watch this short explainer for a practical look at how it works:
. The next step is straightforward: request a tailored quote and get your rental income covered before it needs to be.
Sources
For more detail on inspections and property condition ahead of a new tenancy, see this guide to rental property inspections. For the full breakdown of what’s covered under rental income protection, read the complete guide to rental income protection.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
- Landlord insurance: Protect your rental investment
- Landlord insurance: Protecting your rental investments – LOCALMONEY
- Rental insurance in South Africa: your guide to coverage – Entrepreneur Hub SA