
When a tenant breaks a lease, you typically face three costs: lost rent until you find a new tenant, reletting expenses such as advertising and agent commission, and legal or eviction fees if the tenant refuses to leave. Rental income and eviction insurance can cover these losses, but only when your policy wording allows it and you have followed the correct legal process. The steps below show you exactly what to check and gather first.
TL;DR:
- Insurance coverage for early lease termination often requires explicit endorsement and adherence to strict legal procedures, including prompt notification and proper documentation.
- Reletting costs, legal fees, and repairs are the main financial losses to prove and mitigate through timely actions like advertising, inspections, and keeping receipts.
- Self-help eviction methods such as changing locks or removing belongings without court approval can void insurance claims and are illegal under South African law.
- Insurers expect landlords to show active efforts to relet the property, including advertising and record-keeping, to successfully claim loss if a tenant breaks a lease early.
- To avoid disputes, landlords should handle deposits, notice periods, and legal procedures carefully, always following the law and documenting each step.
Table of Contents
- What landlords lose when a tenant ends a lease early
- The legal framework that affects eviction and claims
- How rental income and eviction insurance responds to early termination
- Common claim pitfalls and reasons insurers reject or reduce claims
- Step-by-step checklist: evidence to gather and act on now
- How to reduce the financial hit before it happens
- How we support landlords through early-termination claims
- How our rental income and eviction cover can protect you
- Sources
- FAQ
What landlords lose when a tenant ends a lease early
The financial hit from an early lease termination rarely stops at one missed rent payment. You carry the cost of an empty unit until you find a replacement tenant, and the law expects you to act quickly to limit that loss rather than let the property sit vacant.
Beyond lost rent, reletting itself costs money: new advertising, agent commission, and tenant screening all add up before a single rand of new rent arrives. If the property needs repairs once the tenant leaves, deposit funds only cover documented damage, and any shortfall comes out of your pocket. When a tenant refuses to leave voluntarily, legal and eviction costs join the list, and these can escalate quickly if the matter reaches a tribunal or court.
- Lost rent: the gap between the tenant leaving and a new tenant moving in, reduced by how quickly you can show you tried to relet.
- Reletting costs: advertising, agent commission, and screening fees for a replacement tenant.
- Repair costs: work needed before the unit is rentable again, offset against the deposit where damage is properly documented.
- Legal and eviction costs: tribunal or court fees and attorney costs when a tenant does not leave voluntarily.
The legal framework that affects eviction and claims
South African law shapes both what you can lawfully do when a lease breaks down and whether an insurer will honour your claim. Getting the process wrong can undo a valid claim just as quickly as a badly worded policy.
- Under section 14 of the Consumer Protection Act, a tenant on a fixed term lease can cancel with 20 business days’ written notice, and you may recover only a reasonable cancellation penalty, never a punitive one.
- The Rental Housing Act sets out requirements for joint inspections, deposit handling, and gives the Rental Housing Tribunal jurisdiction over many landlord and tenant disputes.
- The Prevention of Illegal Eviction Act requires you to follow a court or tribunal process to remove an occupant; self-help eviction, such as changing locks or removing belongings yourself, is unlawful and can undermine any later claim.
- You carry a common law duty to mitigate your loss, which means showing that you took reasonable steps to relet the property rather than letting rent losses accumulate unchecked.
These rules exist to protect both parties, but for you as landlord they also form the backbone of what an insurer will expect to see before paying out.
How rental income and eviction insurance responds to early termination
Rental income and eviction insurance is designed for exactly this situation: tenant non-payment, early termination where the policy allows, and absconding are among the perils typically insured. The cover exists to soften the financial blow, but it responds within conditions rather than automatically.
Insurers commonly expect prompt notification once a problem arises, proof that you tried to mitigate the loss, and evidence that any eviction followed the correct legal route rather than a shortcut. Short-term insurance policies in South Africa operate under the Policyholder Protection Rules, which govern disclosure, fair claims handling, and how insurers must communicate policy terms and cancellations. Reading the policy wording carefully matters more here than with almost any other type of cover, because the definition of “early termination” and the documents required to prove it vary between insurers.
- Non-payment and absconding are usually core covered perils.
- Early termination cover often needs an explicit endorsement rather than being automatic.
- Legal support for eviction is frequently offered as an add-on, worth checking before you need it.
- Prompt notification and mitigation evidence are near-universal conditions for a successful claim.
Pro Tip: Ask your broker to confirm in writing whether early lease termination is covered by default or requires a separate endorsement, before you need to rely on it.
Some rental income insurance products offer coverage for tenant non-payment, early lease termination, and absconding, alongside legal support for eviction and tenant default cases, sometimes with no waiting period before cover begins.
Common claim pitfalls and reasons insurers reject or reduce claims
Most repudiated claims share a handful of avoidable mistakes. Knowing them in advance protects both your legal position and your insurance payout.
- Self-help eviction: changing locks, removing a tenant’s belongings, or cutting off utilities without a court order breaches PIE eviction procedure and can void your cover entirely.
- Failing to mitigate: leaving a unit vacant without advertising it or showing it to prospective tenants weakens or defeats a lost-rent claim.
- Poor documentation: no dated proof of reletting attempts, such as advert screenshots or viewing logs, makes it hard for an insurer to assess the loss fairly.
- Non-disclosure: withholding material facts at policy inception, such as a tenant’s known payment history, can be grounds for repudiation under the Policyholder Protection Rules.
- Missed timing: notifying the insurer late, or after a cancellation deadline under your policy, can forfeit an otherwise valid claim.
Step-by-step checklist: evidence to gather and act on now
Once a tenant gives notice or disappears, the order in which you act matters almost as much as what you do. Move through these steps methodically rather than reactively.
- Secure written proof of the tenant’s cancellation notice or evidence of abandonment, including dates.
- Take date-stamped photographs and complete an inventory of the property’s condition as soon as you gain access.
- Arrange a joint inspection with the tenant where possible, or document your attempts to arrange one.
- Keep every receipt for repairs, cleaning, advertising, and agent fees connected to reletting.
- Record all communications with the tenant, agent, and any prospective replacement tenants.
- Show active reletting efforts, including advert copy, posting dates, viewing logs, and application forms received.
- Notify your insurer promptly and supply the lease agreement, cancellation notice, any tribunal or court order, invoices, and your mitigation evidence together.
A single piece of evidence often decides a claim: a dated record of active reletting efforts, such as an advert posting date or an agent’s invoice (Department of Human Settlements guidance). Without it, insurers tend to treat an avoidable vacancy as the landlord’s own fault rather than an insured loss.
How to reduce the financial hit before it happens
Prevention costs far less than a claim. The landlords who recover fastest from a broken lease are usually the ones who set things up correctly from the start.
Screen every applicant properly and handle deposits strictly in line with the Rental Housing Act, since tribunal practice expects joint inspections and receipts before any deduction. Write lease clauses that comply with the CPA and Rental Housing Act, with clear notice periods so there is no ambiguity when a tenant wants to leave early.
- Choose cover that includes reletting costs and eviction legal fees, not just rent shortfall.
- Set an excess level you can comfortably absorb, balanced against the premium you are willing to pay.
Pro Tip: Re-advertise a vacant unit the same week a tenant gives notice, and keep the listing live, so your mitigation record starts immediately rather than after the fact.
How we support landlords through early-termination claims
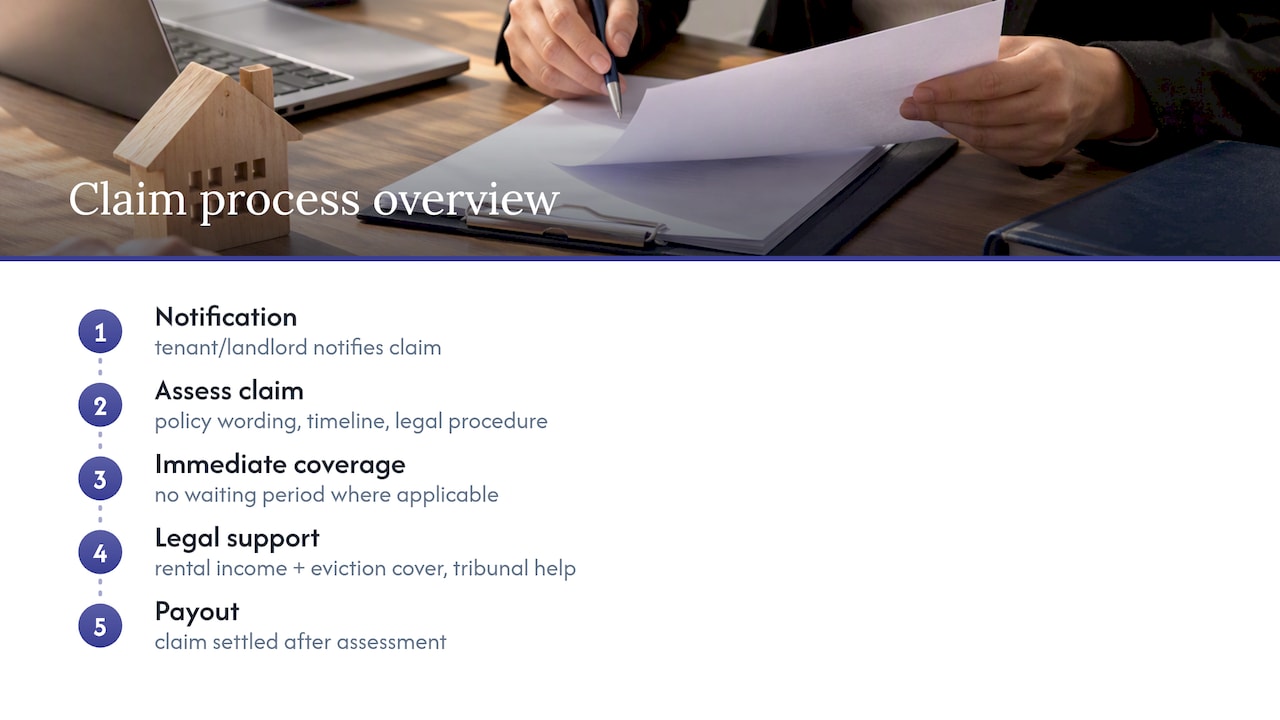
We built our guides and checklists around the practical reality landlords face when a lease breaks down unexpectedly, because coverage is only useful when you know how to use it. When we assess a claim, we look closely at the policy wording, the timeline of events, and whether legal procedure was followed correctly, since these three factors determine most outcomes.
Our approach favours immediate coverage with no waiting period, and we pair rental income and eviction cover with legal support for eviction and tenant default cases, so you are not left navigating tribunal procedure alone. For a walkthrough of how a claim moves from notification to payout, this short video is worth five minutes of your time:
— Coert
How our rental income and eviction cover can protect you
You now know the exposure: lost rent, reletting costs, and legal fees if eviction becomes necessary. Rental income insurance products can safeguard income against tenant non-payment, early lease termination, and absconding, with options for legal support for eviction and tenant default cases, and may include no waiting period before cover begins.

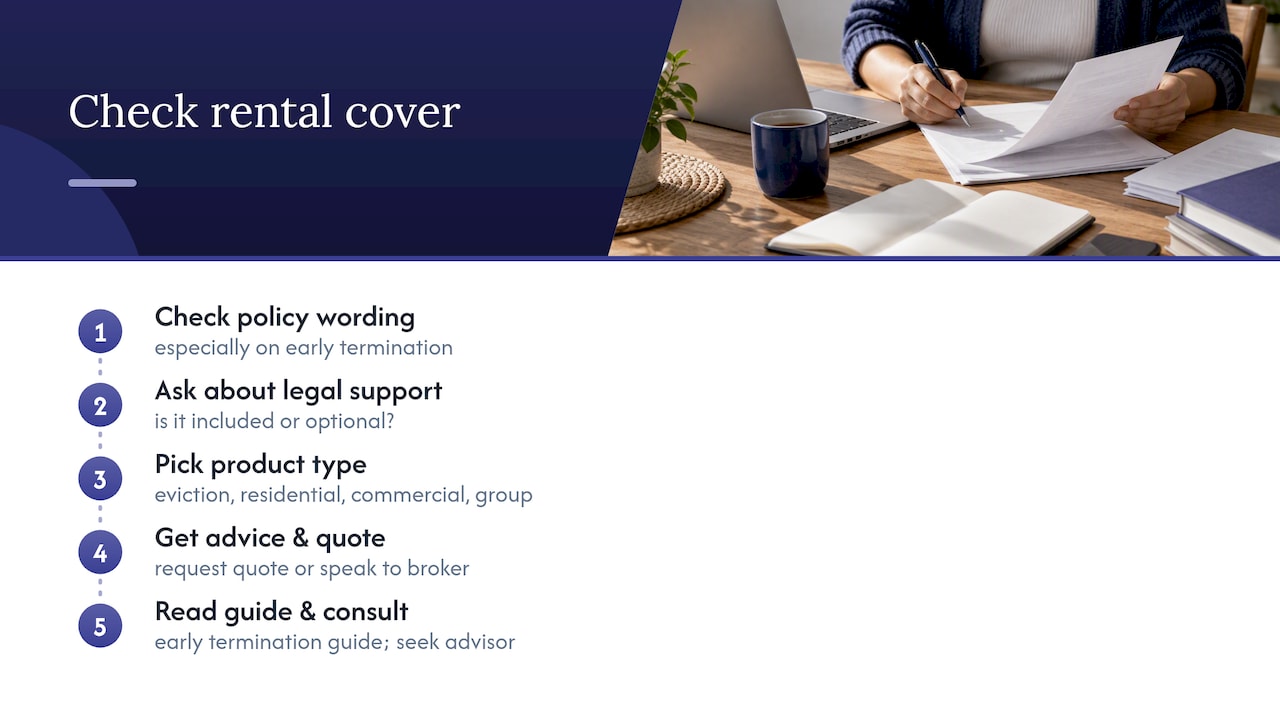
Tailored cover through eviction insurance, residential rental insurance, commercial rental insurance, or group rental insurance may be available depending on your property portfolio. Before you buy, always check the policy wording on early termination and ask whether legal support is included or optional, since this is where most disputes with insurers begin.
Request a quote from Rental Income Insurance today, or speak to a broker about which product fits your property and your risk. For more detail on how the cover pays out in practice, read our guide to early lease termination insurance before you commit.
This article is general information, not a substitute for advice from a qualified financial advisor. Consult a qualified financial professional about your own circumstances before acting on anything here.
Sources
- South African Government — Consumer Protection Act (s.14) guidance
- Justice Department practice guidelines — eviction procedures (PIE)
FAQ
Can I break my lease without financial consequences?
Generally no. Under section 14 of the Consumer Protection Act, a tenant can cancel a fixed term lease early by giving 20 business days’ written notice, but the landlord can still recover a reasonable cancellation penalty. The exact amount depends on how quickly the landlord can find a replacement tenant.
What happens if I break lease and the landlord can’t relet quickly?
The landlord carries a duty to mitigate the loss, meaning they must actively try to find a new tenant rather than simply claiming lost rent indefinitely. If they can show genuine reletting efforts and still face a vacancy, insurers and tribunals generally treat the shortfall as a legitimate loss.
What are the penalties for breaking a lease early?
Penalties are meant to be reasonable, not punitive, and are usually calculated against how long it takes to find a new tenant and the landlord’s reletting costs. There is no fixed penalty figure in law, since tribunal decisions assess this case by case based on mitigation efforts.
Does rental income insurance cover the cost of breaking a lease?
It can, when the policy wording specifically includes early lease termination and the landlord has followed the correct legal process and notified the insurer promptly. Cover for this scenario is often available as part of a rental income or eviction insurance product, but always ask whether it applies automatically or needs a separate endorsement.
How to break a lease legally as a landlord dealing with a defaulting tenant?
A landlord cannot simply remove a tenant; eviction must follow the process set out under the Prevention of Illegal Eviction Act, which requires a court or tribunal order. Self-help eviction, such as changing locks, is unlawful and can also invalidate an insurance claim tied to the same incident.