
If your rental property or a tenant accidentally damages a neighbour’s property, the part of your policy most likely to respond is landlord or property owner liability cover, not your rental income protection. Check the liability section of your schedule first, then notify your insurer straight away and start saving photos, messages and repair quotes as evidence.
TL;DR:
- Liability cover, not rent protection, typically responds to accidental damages caused by tenants or properties to neighbors.
- Policy exclusions for structural failure, wear and tear, or malicious acts can prevent claims from paying, regardless of broad wording.
- Responsibility depends on control and lease terms, with maintenance obligations often clarifying whether landlord or tenant is liable.
- Act quickly by documenting damage, notifying the insurer promptly, and keeping records to enhance the likelihood of claim acceptance.
- Disputes over liability can be challenged through the Short Term Insurance Ombud if the insurer rejects a claim or interpretation is uncertain.
Table of Contents
- What parts of a landlord policy might pay a neighbour’s damage
- How policy wording, limits and exclusions decide whether a claim pays
- Who is legally liable: control, lease allocation and worked examples
- Step by step claims and dispute procedure, including Ombud options
- Practical actions landlords can take now to reduce risk and close gaps
- Treating liability and rental income cover as complementary protections
- How Rental Income Insurance can help with cover, quotes and claims guidance
- FAQ
- Sources
What parts of a landlord policy might pay a neighbour’s damage
Two sections of a landlord policy do very different jobs, and mixing them up costs landlords time during a claim. Property owner liability, sometimes called public liability, covers sums you become legally liable to pay when your property or your tenant causes accidental physical damage to someone else’s tangible property. Nedbank’s homeowner policy wording defines this cover as responding to accidental physical loss or damage that occurs and is reported during the insurance period, subject always to the schedule, limits and exclusions.
Rental income cover sits in a different part of the policy entirely. It typically pays your lost rent or the cost of alternative accommodation when your rental property becomes uninhabitable, not the bill for repairing your neighbour’s fence or wall.
- A tenant’s leaking washing machine that floods the unit next door usually falls to liability cover, not rental income cover.
- A collapsed boundary wall traced to poor maintenance may trigger liability cover, subject to the exclusions in your schedule.
- Lost rent while your own property is repaired after such an incident is where rental income cover does its work.
Whether liability cover actually pays depends entirely on your policy wording and schedule rather than the label on your product. Our guide to property damage liability for South African landlords walks through this distinction in more depth.
How policy wording, limits and exclusions decide whether a claim pays
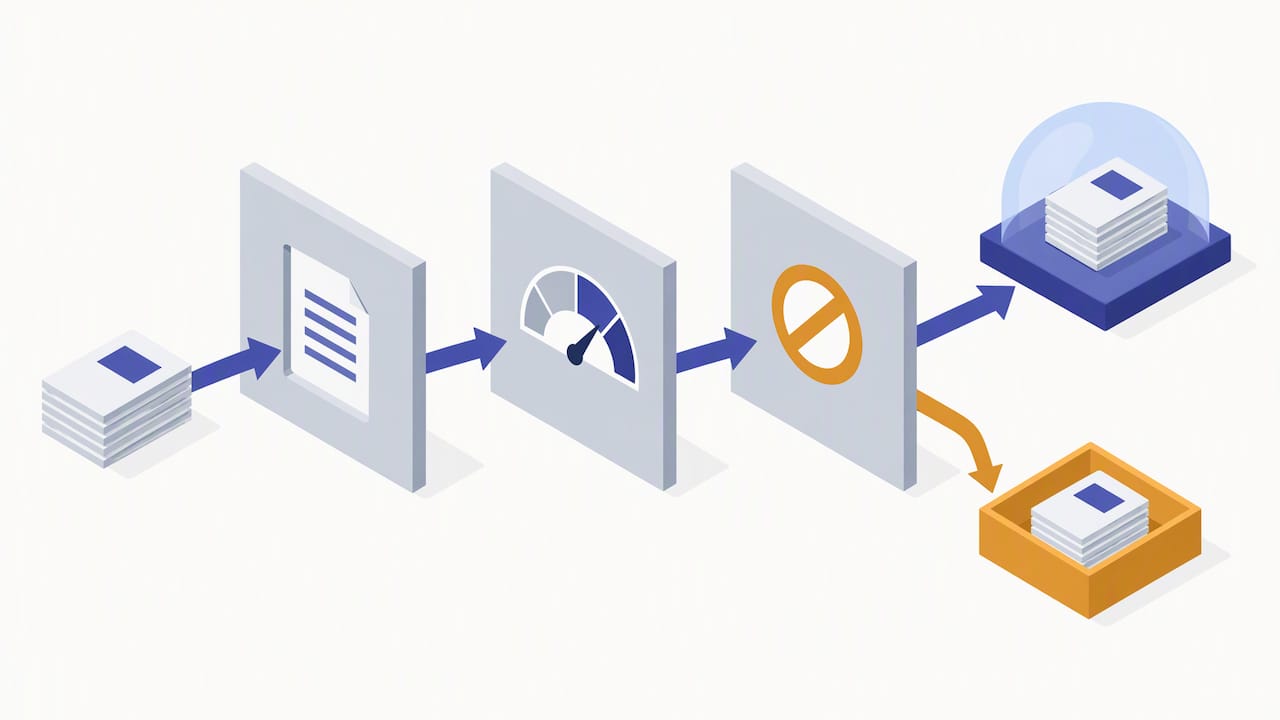
A liability section can look generous on paper and still exclude the exact scenario you face. Three figures in your schedule determine the outcome of any claim: the limit of indemnity, which caps the maximum payout; the excess, which you pay before cover kicks in; and the list of named exclusions, which can remove cover entirely for certain causes.
Courts have confirmed that broad “accidental damage” wording does not override specific exclusions. In Hypercheck (Pty) Ltd v Mutual & Federal Insurance Company Ltd, a South African court held that an exclusion for collapse, cracking or weakening of support structures defeated an otherwise wide “any cause” accidental damage extension. The lesson for landlords is straightforward: read the exclusions before assuming the headline wording protects you.
Before assuming a claim will pay, check these five lines on your policy:
- The limit of indemnity stated in your schedule.
- The excess payable for a liability claim.
- Any exclusion for structural failure, collapse or subsidence.
- Any exclusion for wear and tear or lack of maintenance.
- Any exclusion for malicious acts by tenants or occupiers.
Pro Tip: Keep a copy of your policy schedule and wording in one folder so you can check these five lines within minutes of an incident, not days later.
Who is legally liable: control, lease allocation and worked examples
Liability in South African law generally follows duty and control rather than bare ownership. According to Mont Blanc Financial Services, the party responsible for maintaining the area where an incident happens typically carries the exposure, and a lease can shift that responsibility between landlord and tenant.
Two scenarios illustrate how this plays out:
- A structural defect, such as a failing retaining wall the landlord was responsible for maintaining, points towards landlord liability if it damages a neighbour’s property.
- A tenant’s negligence, such as leaving a tap running and flooding next door, points towards tenant liability, though the landlord may still face questions about maintenance or disclosure.
Because the outcome depends on who held the duty to maintain or control the relevant part of the property, a lease that clearly allocates maintenance obligations makes it far easier to work out whose insurance should respond. Mismatches between lease wording and policy wording are a common source of coverage gaps, so it pays to review both together rather than treating them as separate documents. Our landlord obligations guide sets out how maintenance duties typically sit between landlord and tenant.
Step by step claims and dispute procedure, including Ombud options
Acting quickly after an incident protects both your relationship with the neighbour and your claim. The sequence that gives you the best chance of a smooth outcome looks like this:
- Photograph the damage immediately and note the date, time and any witnesses.
- Collect maintenance records, lease documents and any prior correspondence about the affected area.
- Notify your insurer without delay, since timing can affect whether cover applies.
- If the insurer rejects the claim, request written reasons setting out exactly which clause or exclusion applies.
- Follow the insurer’s internal complaints process before escalating further.
- Where eligible, refer the dispute to the Short Term Insurance Ombud.
Prompt notification matters more than many landlords realise. Ombud guidance notes that late notification is a frequent ground for dispute in public liability cases, because it can limit the insurer’s ability to investigate while evidence is fresh.
If your insurer rejects liability, you are not out of options. The Ombudsman for Short Term Insurance accepts disputes over policy interpretation and claims decisions within monetary limits of R5 million or R10 million depending on the type of cover involved, giving landlords a formal route to challenge an insurer’s decision without going straight to court. Where liability clearly rests with a tenant who cannot or will not pay, recovering losses from a deposit or through legal action remains a separate avenue worth discussing with a professional.
Practical actions landlords can take now to reduce risk and close gaps
Prevention and good records do more for a future claim than anything you can do after the damage is done. A dated maintenance log, kept consistently, gives you something concrete to show an insurer or the Ombud if a dispute arises over whether neglect played a role.
- Set a maintenance schedule for boundary walls, drainage, plumbing and anything likely to affect a neighbouring property if it fails.
- Draft lease clauses that clearly allocate maintenance responsibilities and, where appropriate, require tenants to hold their own contents or liability cover.
- Check that your policy includes a landlord liability extension with a limit that reflects the value of nearby properties, not just your own.
- Review your policy alongside your lease with a broker so the two documents do not contradict each other.
Keeping your property well maintained also tends to reduce the kind of incidents that lead to disputes in the first place. For a broader look at upkeep that protects both tenants and neighbours, this guide to energy efficiency in rental properties covers practical maintenance steps worth building into your routine.
Pro Tip: Ask your broker to compare your lease obligations against your policy wording once a year, since both tend to change independently of each other.
Treating liability and rental income cover as complementary protections
Having watched how these claims typically unfold, our view is that landlords who treat liability cover and rental income cover as one combined safety net, rather than two separate products, end up far better protected. Check your liability wording before anything happens, not after. Act within hours of any incident, not days, and make sure your lease and your policy say the same thing about who maintains what. When a clause is ambiguous or an insurer’s rejection feels wrong, get professional advice rather than guessing.
— Coert
How Rental Income Insurance can help with cover, quotes and claims guidance
We offer Rental Income Insurance built around the gaps landlords actually fall into: lost rent during disputes, eviction costs, and the property damage questions this guide has walked through. Alongside Rental Income Insurance, priced competitively per month, we offer Eviction Insurance, Residential Rental Insurance, Commercial Rental Insurance and Group Rental Insurance, each matched to the way you let your property.

When you are not sure whether your current policy would respond to a neighbour damage claim, we can review your cover and explain where the liability section stands against your lease. Request a quote today and we will talk you through the options that fit your situation. For a closer look at how rental income protection works alongside liability cover, our explainer on rental income insurance is a useful next read, and this short overview covers the same ground:
FAQ
Does homeowners insurance cover accidental damage to a neighbour’s property?
For landlords, it is the property owner liability section of your landlord policy, not your buildings or rental income cover, that typically responds to accidental damage you or your tenant cause to a neighbour’s property. Cover depends on your schedule, limits and exclusions, so always check the wording rather than assuming the label guarantees a payout.
What is the difference between landlord and tenant liability for damage?
Liability generally follows who controls and maintains the area involved, according to industry guidance on tenant versus landlord liability. A structural issue the landlord was responsible for maintaining usually points to landlord liability, while a tenant’s negligent act usually points to tenant liability.
What should I do immediately after my tenant damages a neighbour’s property?
Photograph the damage, note witness details and gather any maintenance or lease records relevant to the area involved. Notify your insurer promptly, since Ombud guidance shows that late notification is a common reason insurers dispute liability claims.
Can I dispute an insurer’s decision to reject a neighbour damage claim?
Yes. Request written reasons from your insurer, follow its internal complaints process, and if you remain unsatisfied you can refer the matter to the Short Term Insurance Ombud, which handles disputes within set monetary limits depending on the cover involved.
Does rental income insurance pay for a neighbour’s property damage?
No. Rental income cover is designed to replace lost rent or pay for alternative accommodation when your rental property is uninhabitable, not to settle a neighbour’s repair bill. Our Rental Income Insurance is built specifically for that income protection role, separate from liability cover.
Sources
- Nedbank homeowner policy wording (property owner’s liability)
- Hypercheck (Pty) Ltd v Mutual & Federal Insurance Company Ltd (case law)
- Terms of reference of the Ombudsman for Short‑Term Insurance
- Tenant vs landlord public liability | Mont Blanc Financial Services
- Ombudsman schemes and dispute guidance (Lawforall)